A mortgage preapproval can turn a home search near the Clinton Presidential Library into a more focused, confident process. Knowing what a lender will review, preparing documents early, and comparing loan options before touring homes can help you respond thoughtfully when the right property appears.
Start With the Numbers That Shape Your Search
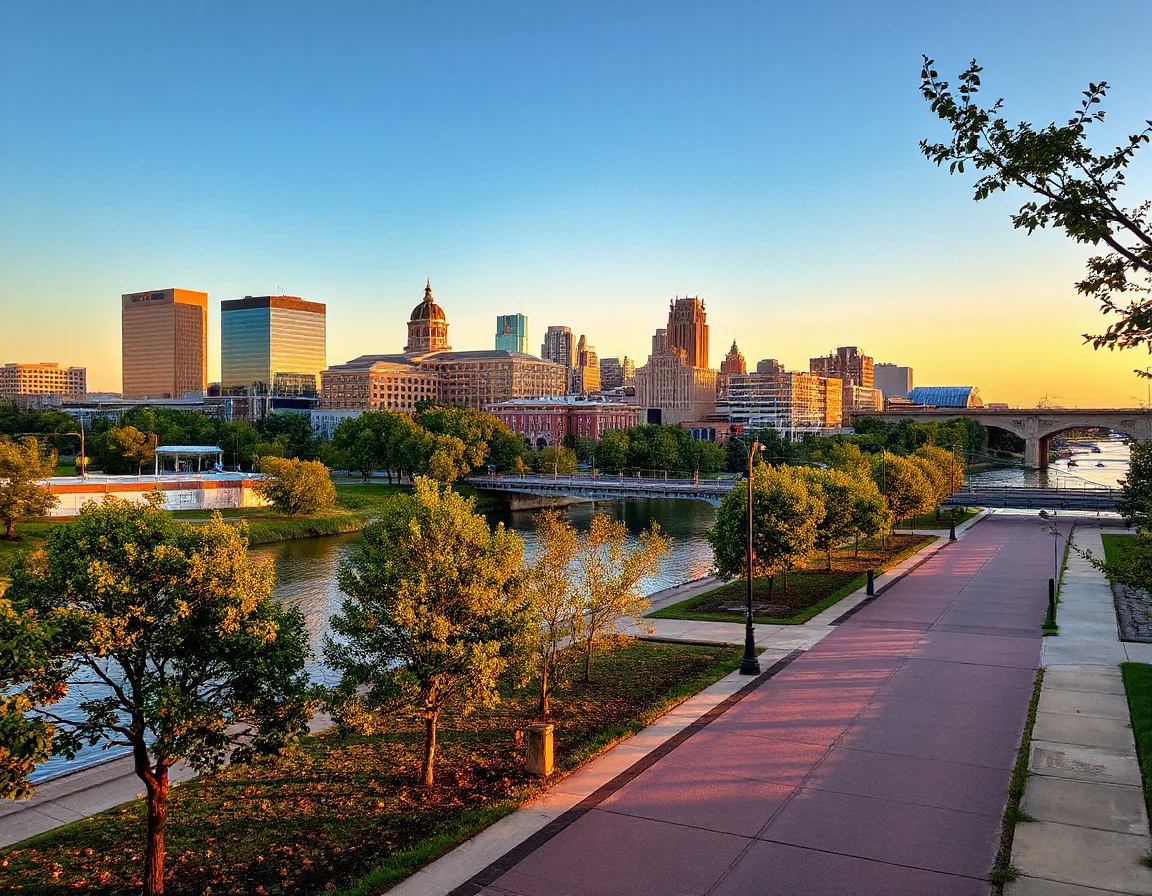
Buying near the William J. Clinton Presidential Library and Museum places you close to one of Little Rock’s most recognizable riverfront destinations, with access to River Market activities, downtown routes, cultural venues, and the Arkansas River Trail. Homes and condos in the broader area can vary widely in age, layout, maintenance needs, association fees, and price. A preapproval gives your search a practical starting point by identifying a price range that reflects both lender guidelines and your own comfort level.
Prequalification and preapproval are not the same thing. A prequalification is often an early estimate based largely on information you provide. A preapproval generally involves a lender reviewing supporting financial documents and, in many cases, your credit profile. It is still not a final loan approval; the property, appraisal, title work, updated finances, and underwriting conditions remain part of the process. Yet a well-supported preapproval is usually a more useful planning tool when you are ready to make offers.
Ask the lender to explain the full monthly payment rather than focusing only on a purchase price. The estimate may include principal, interest, property taxes, homeowners insurance, mortgage insurance when applicable, and condominium or homeowners association dues. A building with a lower list price can have a different monthly cost than expected if association fees, insurance requirements, or maintenance obligations are higher. Looking at the complete picture helps you compare homes on consistent terms.
A preapproval amount is a lending ceiling, not a spending target. Build your search around a monthly payment that leaves room for utilities, repairs, moving costs, and the priorities that matter in your everyday budget.
Before applying, review your available funds for a down payment, earnest money, inspections, appraisal-related costs, lender fees, and closing expenses. Some loan programs allow lower down payments, while others may offer different pricing or mortgage-insurance structures. Your lender can outline program-specific requirements, and an experienced real estate professional can help you consider how those costs fit into an offer strategy. The goal is not simply to qualify; it is to choose terms you can understand and sustain.
Review loan process information
Prepare Documents Before You Fall in Love With a Home
A smooth preapproval conversation starts with organized records. Lenders commonly request identification, recent pay stubs, W-2s or tax returns, bank statements, and information about recurring debts or other financial obligations. If you are self-employed, receive variable income, or have recently changed jobs, plan for additional questions and documentation. Supplying complete records early can reduce avoidable delays when it is time to update your preapproval for a specific property.
Try to avoid major financial changes after beginning the process unless they are necessary and discussed with your lender. New credit accounts, large unexplained deposits, changes in employment, or substantial purchases financed before closing can affect underwriting review. This does not mean everyday life must pause. It means that clear records and prompt communication matter. When a question arises, a lender can explain what documentation may be needed and whether a change could alter your financing options.
Credit is another important part of the conversation, but it should not be treated as a mystery. Request a clear explanation of the credit score range used by the lender, the loan programs available, and any steps that could strengthen your application over time. Avoid trying quick fixes without advice, such as closing longtime accounts or moving money between accounts without keeping a clear paper trail. Practical, documented steps are generally more useful than rushed changes.
If you plan to purchase a condominium, townhome, historic property, or home requiring repairs, mention that early. The type of property can influence appraisal questions, insurance needs, financing eligibility, or association-document review. In areas near the library and riverfront, buyers may encounter a mix of established residences, newer construction, and condo communities. A lender who understands your intended property type can help set realistic expectations before you invest time in tours and inspections.
Keep a simple digital folder for pay records, bank statements, tax documents, and lender messages. Having current files ready can make it easier to refresh a preapproval when a property catches your attention.
Compare Lenders and Read the Details
It can be worthwhile to speak with more than one lender, especially when you want to compare loan programs, rates, estimated closing costs, and communication style. Ask each lender for an easy-to-follow breakdown of the projected payment and cash needed to close. Interest rates matter, but they are only one part of the decision. The annual percentage rate, lender fees, points, lock period, service expectations, and timeline can all affect the overall experience.
Questions are a strength, not a setback. Ask what documents will be needed after you make an offer, how long an appraisal may take, whether your preapproval needs to be refreshed, and what conditions could affect final approval. If a lender quotes a rate, ask whether it is locked and, if not, how a rate lock works. Clear answers let you make comparisons based on facts rather than assumptions.
As you begin touring homes, share your preapproval range with your real estate professional and revisit it when you find a property with distinctive costs. A seller may value an offer that is complete, well-documented, and aligned with the property’s timeline, but every offer should also protect your ability to conduct inspections, review disclosures, and evaluate financing terms. A deliberate approach can be especially helpful when several buyers are interested in the same home.
Search homes near the Clinton Presidential Library
Use Your Preapproval as a Flexible Planning Tool
Preapprovals have expiration dates, and lenders may need updated pay stubs, account statements, or credit information before closing. Keep an eye on those dates while you search, particularly if your timeline extends beyond a few months. If your budget, employment, savings, or desired loan type changes, notify the lender early rather than waiting until an offer is underway.
The most useful preapproval is one that supports informed decisions. It can clarify your budget, reduce last-minute surprises, and help you focus on properties that match your financial plan near the Clinton Presidential Library and throughout Little Rock. With records organized, questions answered, and a trusted team in place, you can move from browsing to making an offer with a clearer view of the road ahead.