A condo’s purchase price is only one part of the budget. Association dues, parking arrangements, insurance, and potential assessments can change what ownership costs each month. Here’s how to compare those expenses before you commit to a River Market property.
Start with the full monthly picture
A River Market condo can put Little Rock’s dining, entertainment, and riverfront attractions within reach, but convenience comes with financial details worth examining. Two similarly priced units may have very different monthly costs depending on what the association covers and how parking is arranged. Begin your search with a budget that accounts for the property and the building around it.
Start with your estimated mortgage principal and interest, property taxes, and insurance. Then add the monthly condo association fee, parking charges, utilities not included in the dues, and any other recurring costs. Ask your lender for a personalized estimate rather than relying solely on an online calculator; taxes, insurance premiums, and loan terms will depend on the property and your circumstances.
For illustration, suppose a buyer estimates $1,550 for principal, interest, and taxes, $350 in association dues, $125 for parking, and $100 for condo insurance. The total is $2,125 per month, before utilities, maintenance inside the unit, and other expenses. These figures are examples, not River Market prices or a loan quote.
A parking space and association dues can add hundreds of dollars to a monthly estimate. Compare homes using the total cost, not the listing price alone.
It also helps to set aside money for expenses that do not arrive monthly. Moving costs, repairs inside the unit, insurance deductibles, and future dues increases can put pressure on a budget that leaves no margin. A separate emergency fund gives you more room to respond when an unexpected bill arrives.
Understand what the association fee covers
Condo dues generally support shared expenses, but the details vary by association. One building’s fee might include certain utilities, exterior maintenance, common-area cleaning, or amenities; another may charge owners separately for services that seem similar. Request a current breakdown and confirm which expenses remain your responsibility.
Look beyond the amount due today. Ask for recent budgets, financial statements, meeting minutes, and any available reserve study. These documents can help you understand how the association plans for major shared expenses, such as roof work or equipment replacement. They can also reveal whether dues have changed and whether significant projects are being discussed.
A special assessment is an additional charge an association may levy for an expense not fully covered by its regular budget or reserves. Ask whether any assessment is approved, pending, or under discussion, how much the unit would owe, and when payments are due. If one exists, have your agent and closing professional clarify in writing how it will be handled in the purchase.
Review the association’s insurance as well. Its master policy may cover certain shared elements, while your individual policy may need to cover belongings, liability, interior improvements, or other items. An insurance agent can compare the building’s policy and governing documents with your proposed coverage so you understand potential gaps and deductibles.
Put the parking arrangement in writing
Parking can be as important to the budget as the condo fee, and a listing description may not explain the whole arrangement. A space might be included with the unit, assigned by the association, leased separately, or available under a different set of rules. Do not assume that a space visible during a showing automatically transfers to the buyer.
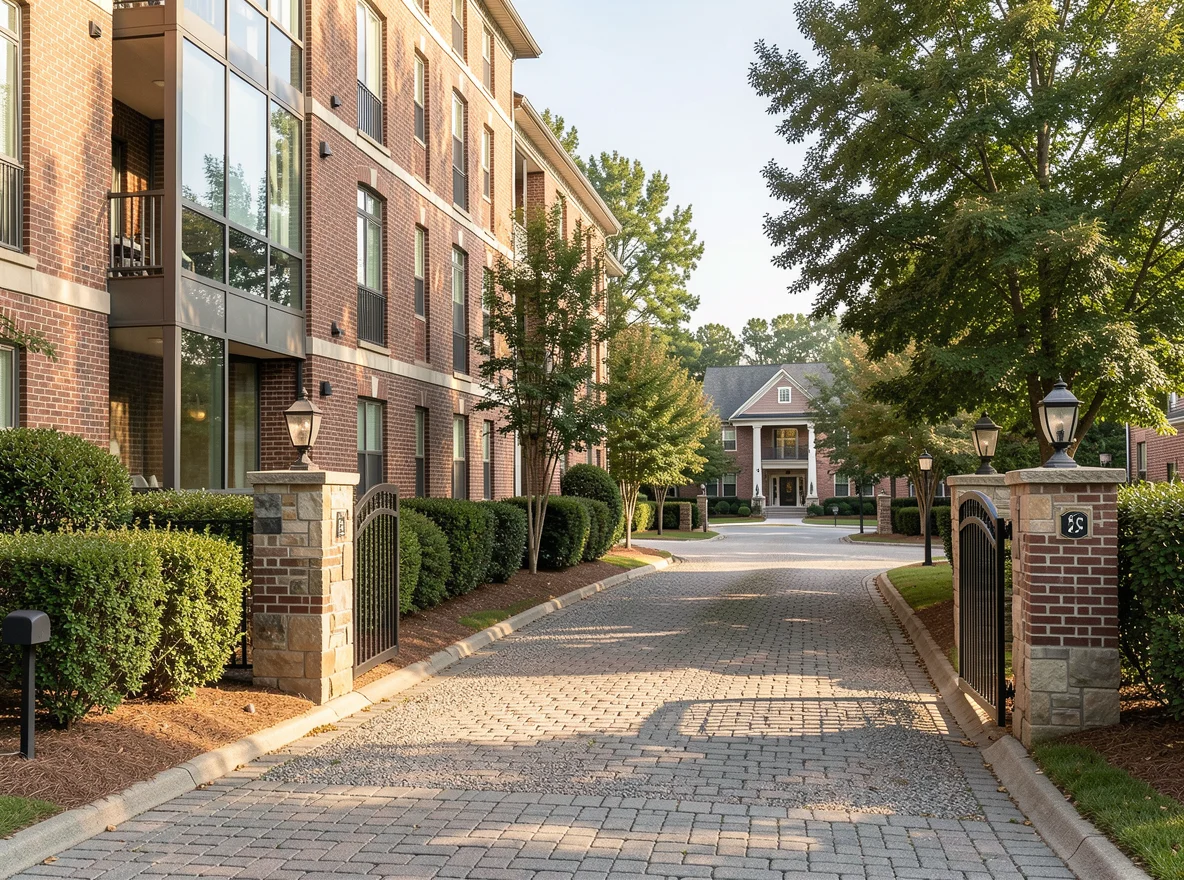
Ask whether the space is deeded, a limited common element, assigned by the association, or rented under a separate agreement. Have the seller or association provide the documents showing the arrangement, and ask your closing professional how the rights transfer. If parking is leased, confirm the rate, renewal terms, availability, and whether the association or another party can change the agreement.
Consider the practical details too. Check the location and dimensions of the space, access hours, clearance, guest parking rules, and any charges for additional vehicles. If electric vehicle charging matters to you, ask whether it is available and who pays installation, electricity, and ongoing fees. Visit the space in person when possible rather than judging it only from a floor plan.
A parking space shown during a tour is not necessarily included in the sale. Verify the space number, transfer rights, and any recurring charge before removing contract protections.
For a space that is not guaranteed, build a backup plan into your budget. Ask about current alternatives and their terms, but avoid assuming that a nearby space will remain available at the same price. The goal is to know what happens if the preferred arrangement changes.
Check financing and inspection details early
Condo financing can involve questions about both the buyer and the association. Before making an offer, tell your lender that you are considering a condo and share the property details as soon as they are available. Depending on the loan program, the lender may need information about the building’s insurance, finances, ownership, or other project characteristics.
Association dues can also affect the lender’s calculation of your monthly obligations. A preapproval based on a general purchase price may need to be updated once the lender knows the actual dues, taxes, insurance, and parking costs. Ask what documents the lender needs, who will provide them, and whether there are fees for an association questionnaire or other records.
An inspection remains valuable even when the association maintains portions of the building. Discuss the scope with your inspector: the unit’s accessible systems and interior may be reviewed, while shared components may require information from the association or a specialist. Read the governing documents to understand where the association’s maintenance responsibility ends and yours begins.
Work with your agent to understand the deadlines in your offer for financing, inspection, and review of association information. Request documents promptly and leave time for questions. If a concern arises, your available options will depend on the contract and applicable law, so consult your agent and, when appropriate, an attorney.
Explore loan process information
Compare properties with the same checklist
As you tour, create a simple worksheet for each unit. Record the purchase price, estimated mortgage payment, taxes, insurance, association dues, parking costs, included services, and any known assessments. Add notes about reserves, upcoming projects, parking rights, and rules that matter to your intended use of the property. This makes it easier to compare a lower-priced unit with higher dues against another that costs more upfront but includes services you would otherwise pay for separately.
River Market offers access to attractions along the Arkansas River as well as places to dine and gather, but the right purchase still depends on the particulars of the unit and building. Review the numbers and documents with your lender, insurance agent, and real estate professional before deciding what fits. Keisha Walker can help you organize questions as you explore available properties and move toward an informed offer.